Program Spotlight: Conventional Cash-Out — The 84.4% of the Market You Can't Afford to Skip
Every month we spotlight one program from the Loansure Marketing Investment Portfolio™. This month it's the one the data won't stop pointing at: the Conventional Cash-Out Refinance.
One Number First
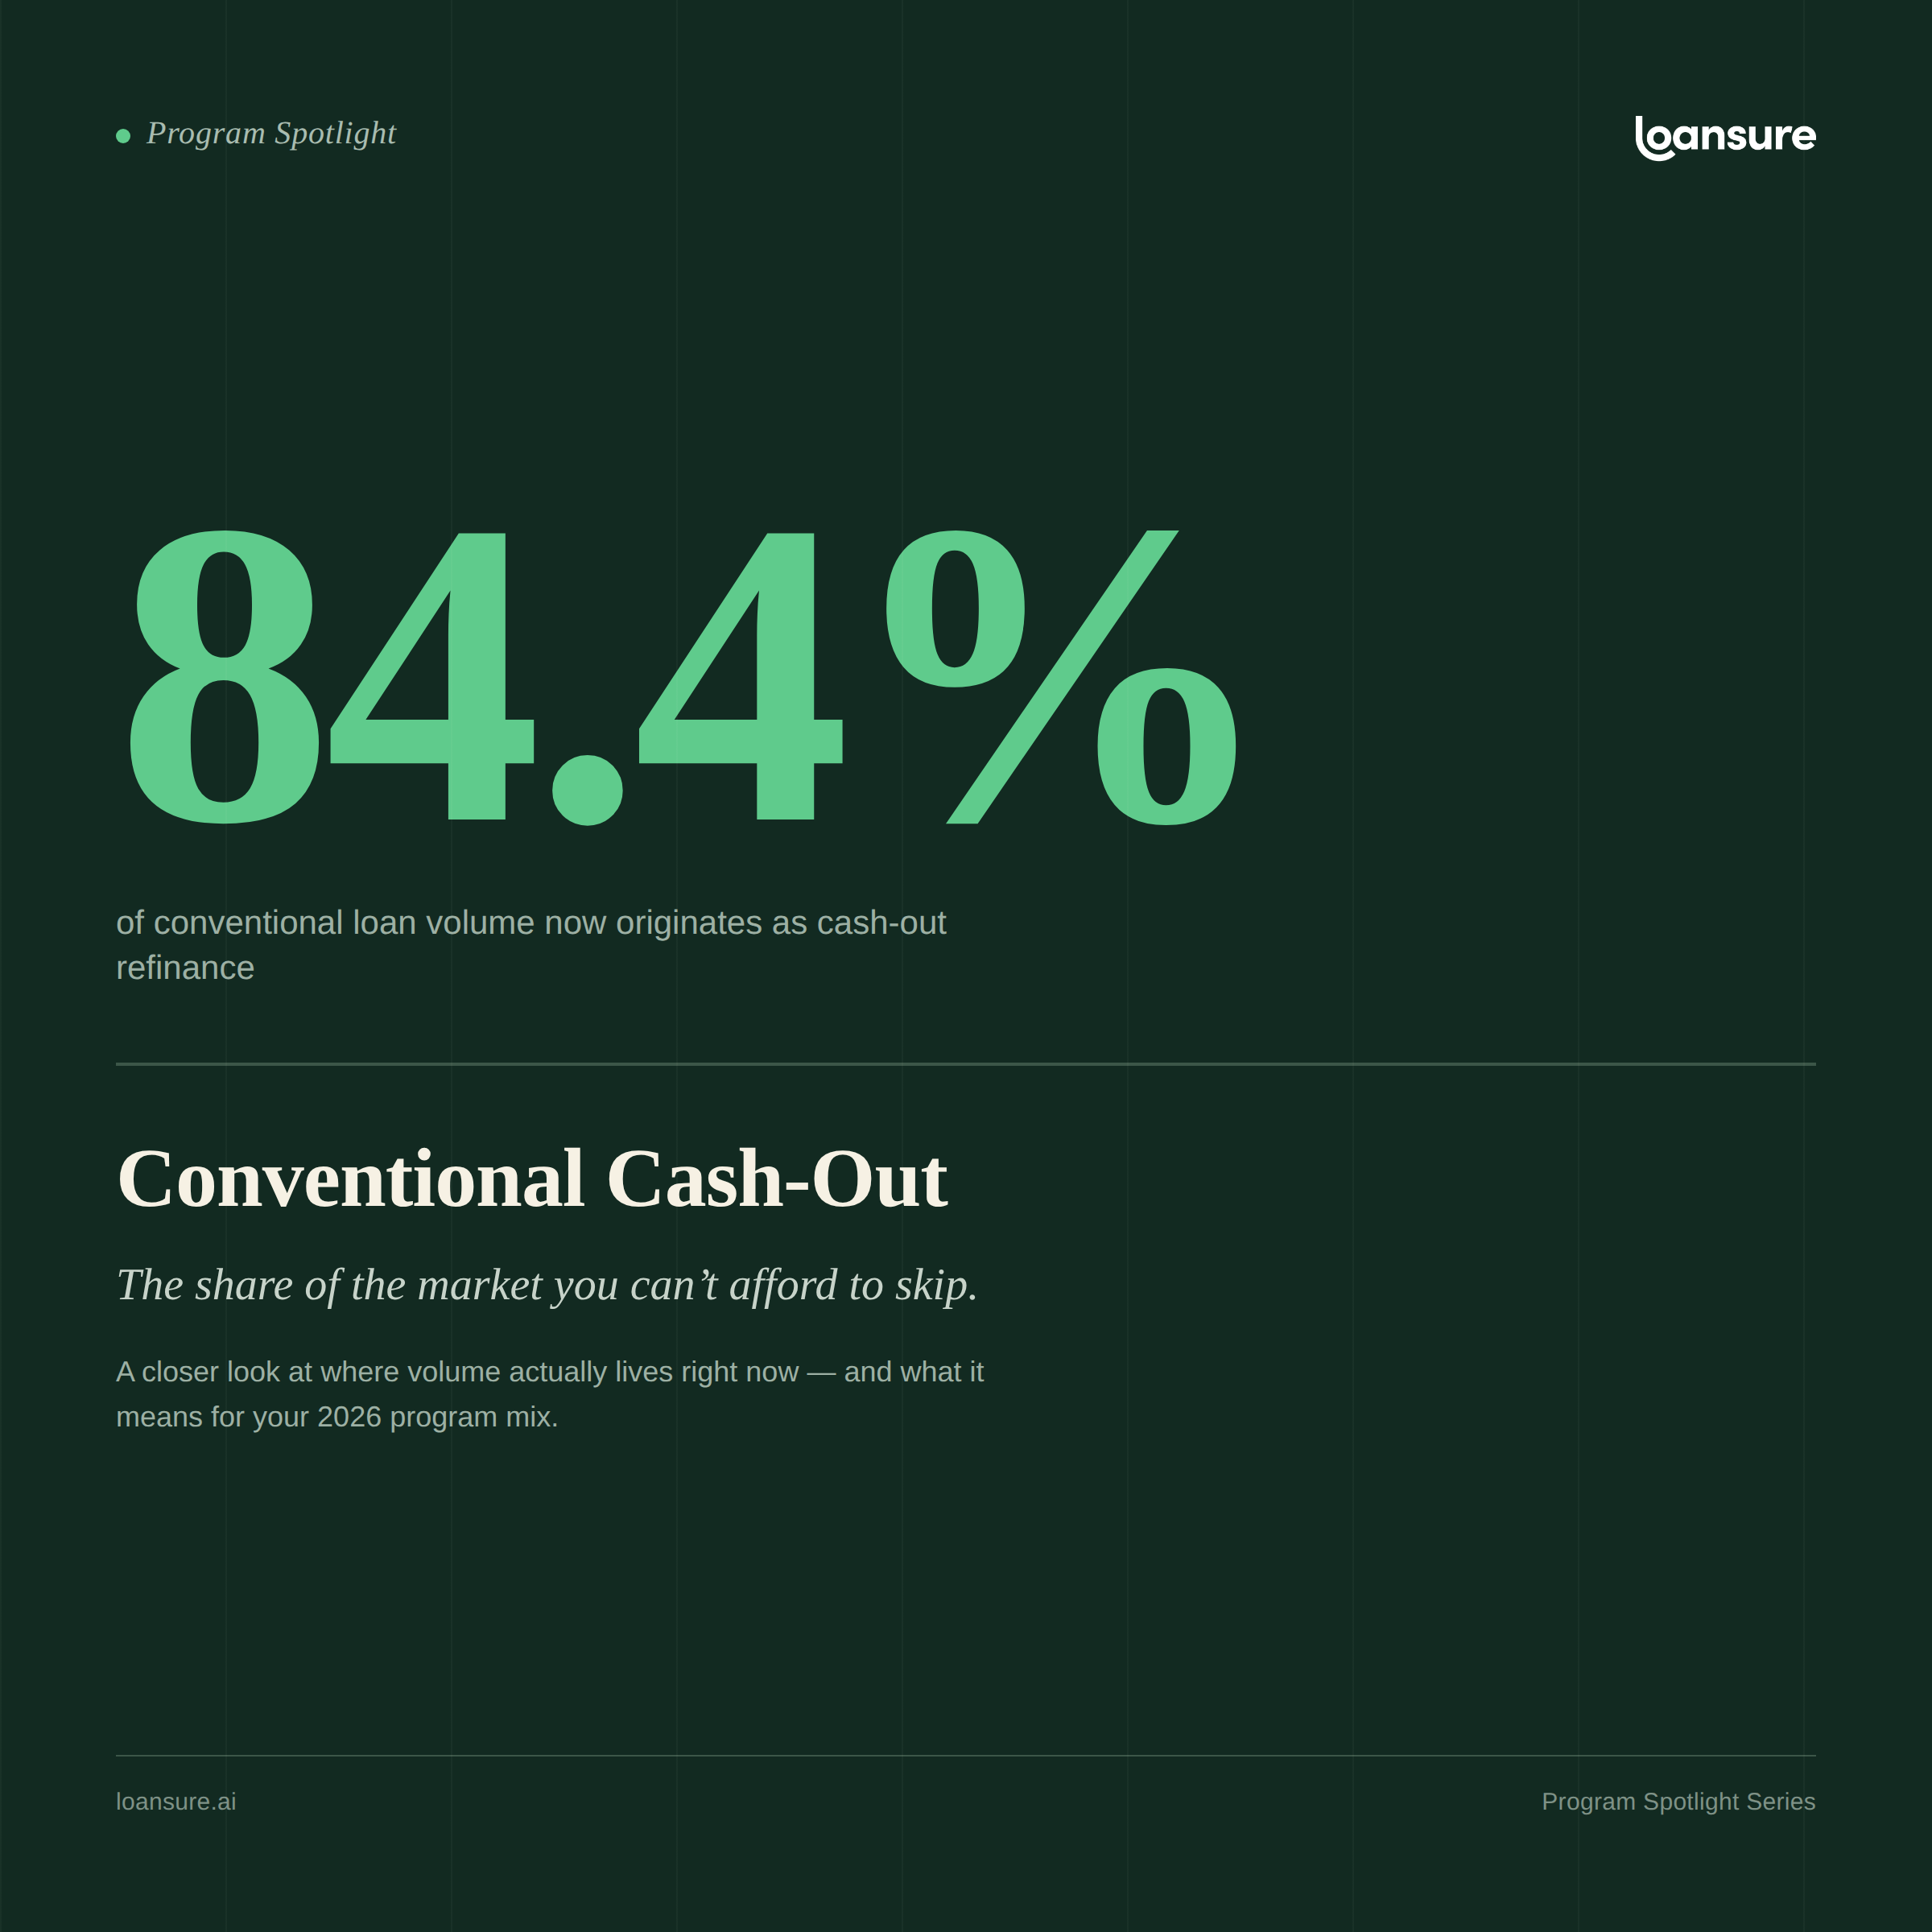
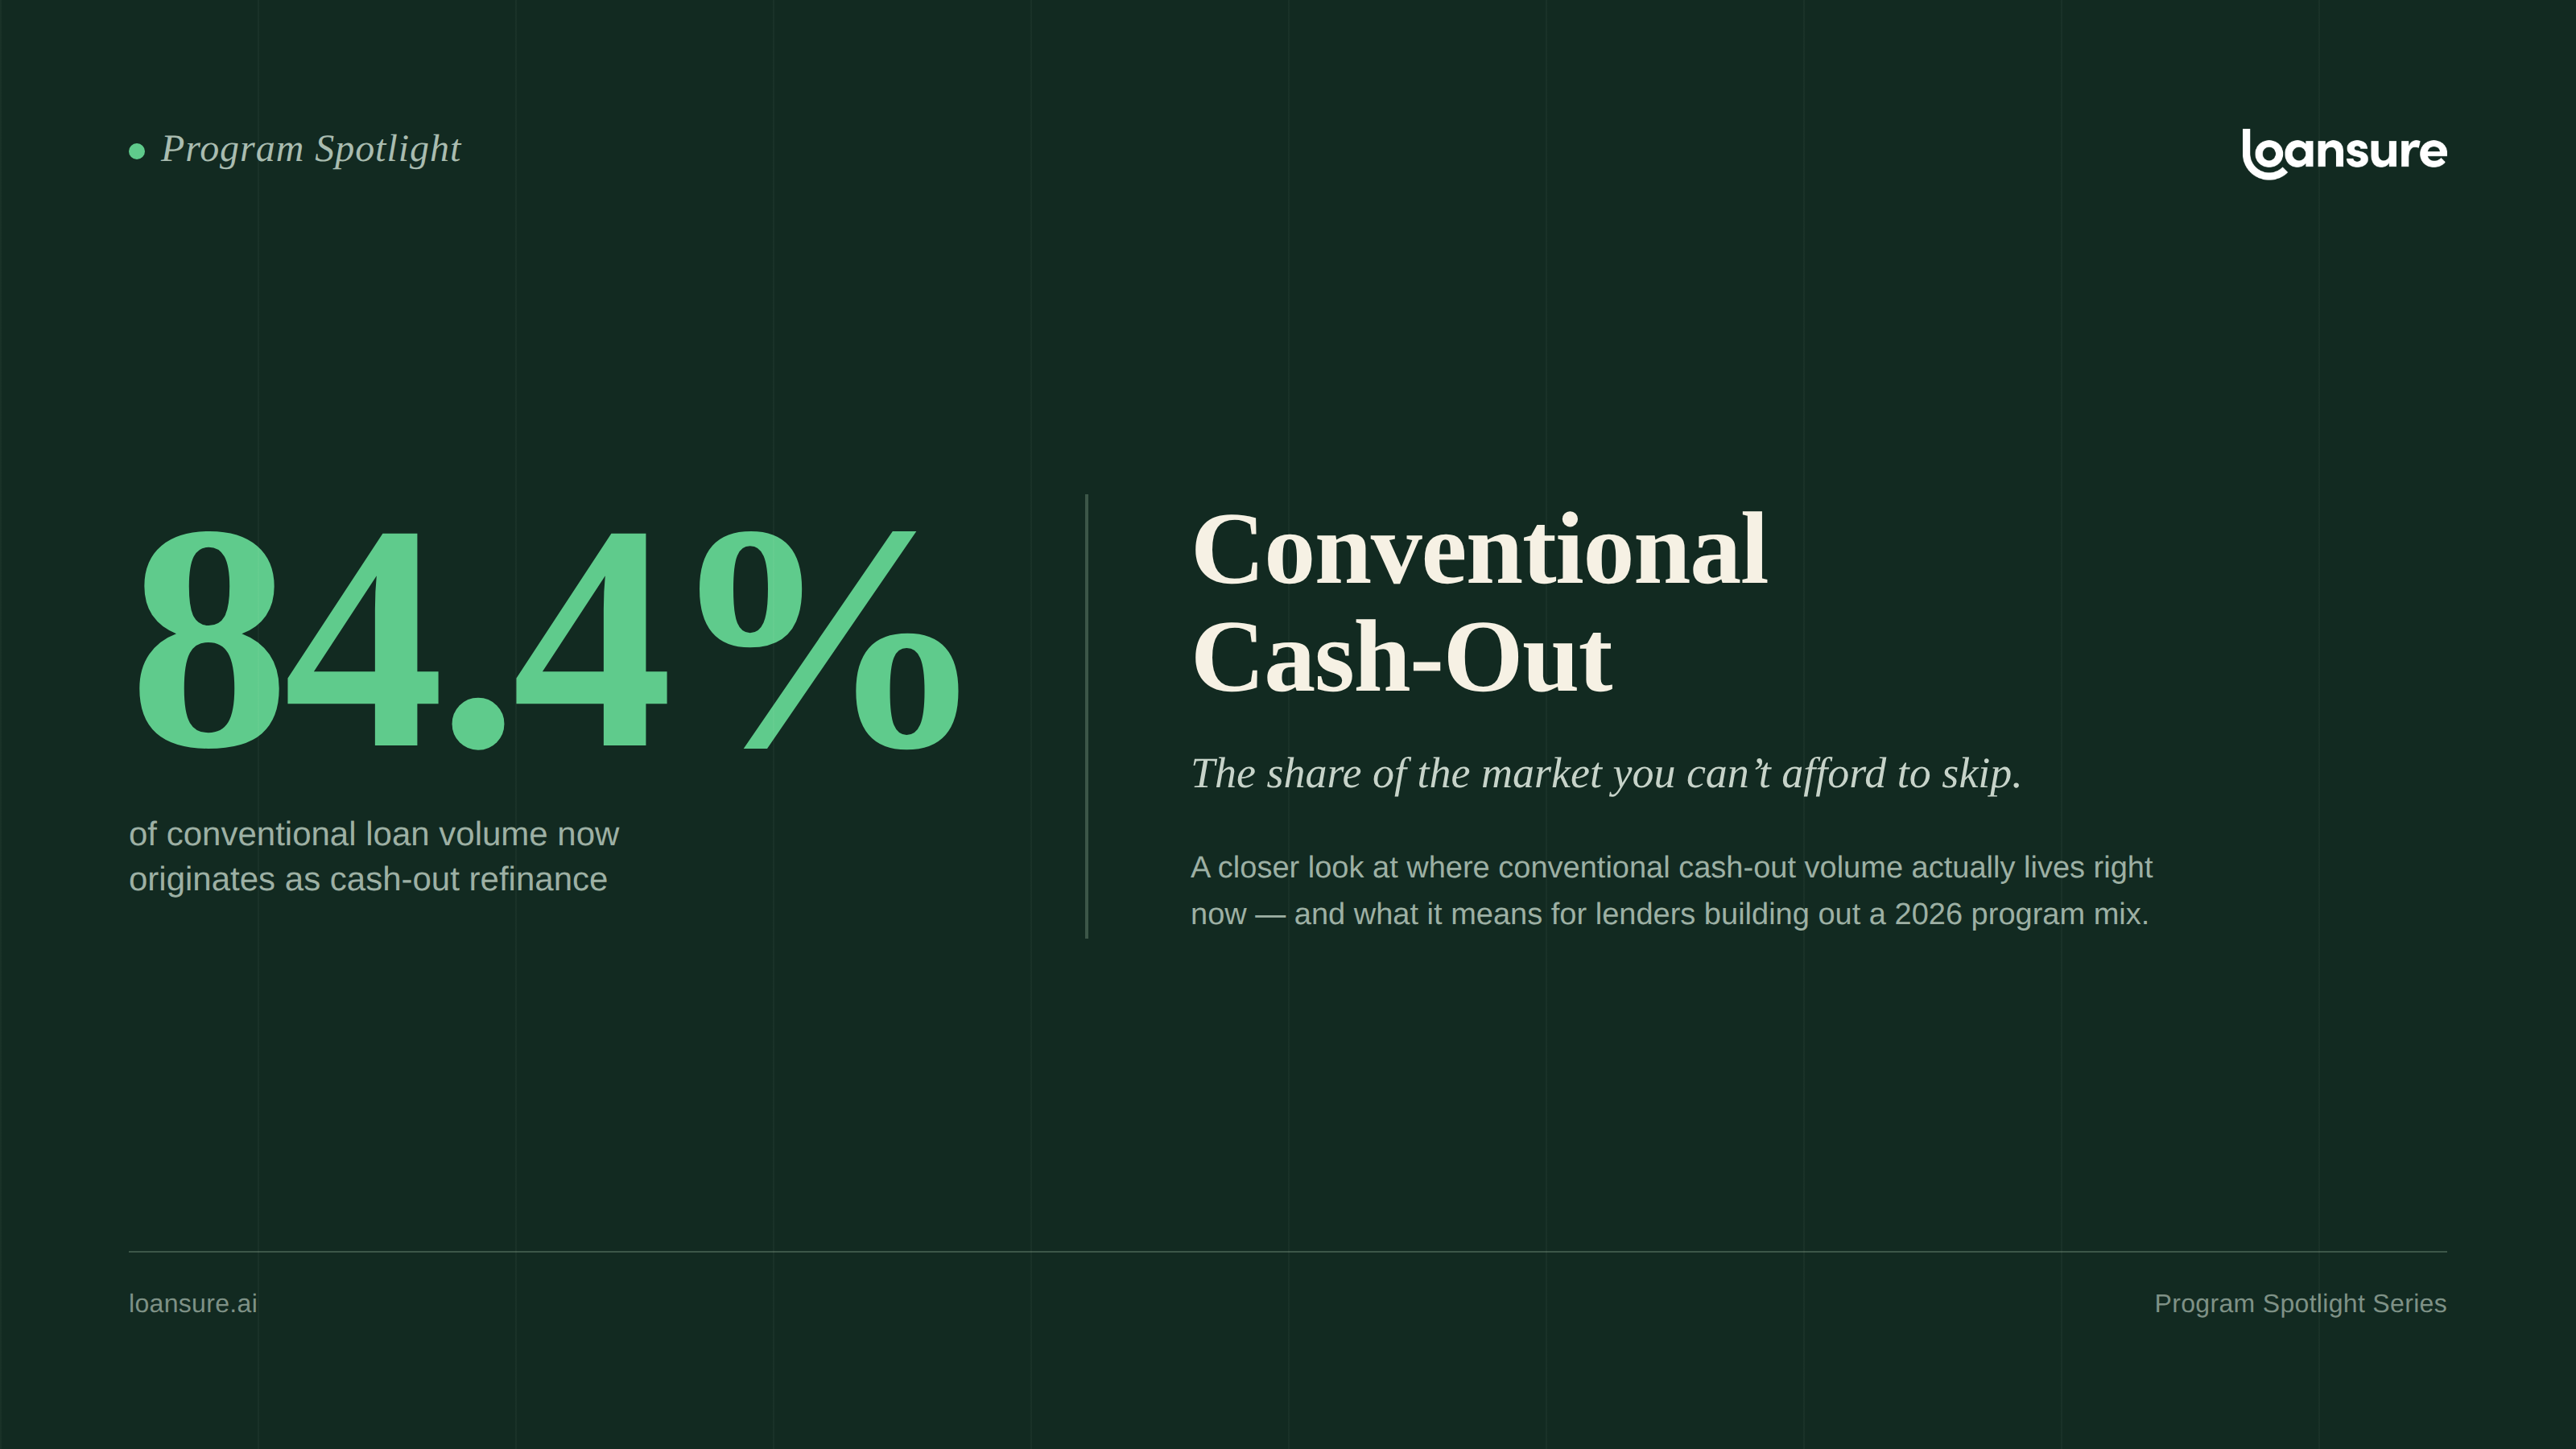
84.4%.
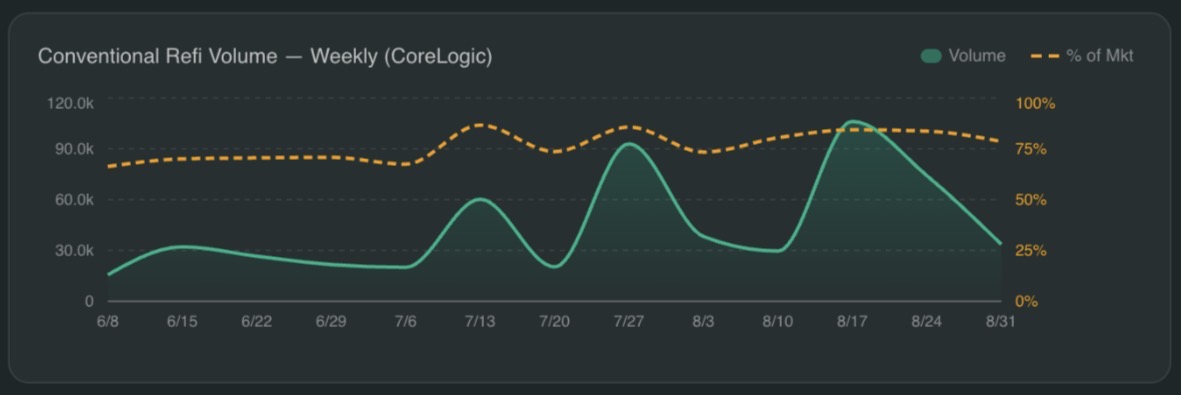
That's the share of the total funded refinance market that conventional refis represent right now, per CoreLogic funded loan data — and cash-out is the engine behind it. Not FHA. Not VA. Conventional.
Read that again if your marketing calendar is still organized around streamlines and rate-and-terms. Any lender not actively running conventional cash-out campaigns is sitting out the overwhelming majority of today's refinance market — and missing the most profitable and predictable growth volume available in 2026.
What the Program Is
A Conventional Cash-Out Refinance replaces an existing mortgage with a new, larger conforming loan underwritten to Fannie Mae or Freddie Mac guidelines. The borrower walks away from closing with the difference in cash — usable for anything: debt payoff, home improvement, a major purchase, a business.
Who qualifies:
- Primary residence up to 80% LTV (75% on second homes)
- Minimum 620 credit score (higher tiers earn better pricing)
- 6-month seasoning from purchase or prior cash-out
- Existing loan must be conventional (not FHA or VA)
- DTI typically capped at 45–50%, loan within conforming limits
Why It Works Right Now
The ideal borrower profile is everywhere: a homeowner who bought 3–7 years ago, has built substantial equity through appreciation, and needs liquidity. Even at a rate modestly above their current one, access to capital justifies the move — because the alternative is carrying credit card balances at rates north of 20%.
This is the structural reality of 2026: the “lower my rate” borrower is rare, but the “I'm sitting on six figures of equity and carrying expensive debt” borrower is the market. Conventional cash-out is how they solve their problem — and how lenders grow when rate-driven volume won't come back.
How the Program Is Performing
Across active Loansure conventional cash-out campaigns:
- Average loan sizes: $300K+ — meaningfully larger balances than government cash-out programs, which means more revenue per funded loan
- Cost per acquisition: mid-two-thousands on average (measured at docs out — application submitted and disclosures sent) and trending in the right direction as campaigns mature and optimization compounds
- Against a $300K+ average loan, that acquisition cost translates to a fraction of a point of loan volume — economics that hold up in any margin environment
And demand is holding: conventional refi applications are up 3% year over year even as the broader refi index cooled — the only major category still positive against last year.
The Bottom Line
The refinance market didn't disappear. It changed shape. It's conventional, it's equity-driven, and it's 84.4% of what's actually funding. Lenders running conventional cash-out campaigns are compounding data, pipeline, and market position every week. Lenders waiting for rates to fall are watching them do it.
Want to see what a conventional cash-out campaign would look like for your team? We'll model your footprint, your capacity, and your projected funnel before you spend a dollar — that's how every Loansure program starts.
Loansure is the mortgage industry's Loan Acquisition System — homeowner-first, data-driven loan acquisition, from targeted outreach to funded outcomes. loansure.ai